Insurance Tips For Windshield Replacement Claims: Get The Most From Your Coverage
Getting your windshield replaced can be a hassle, but knowing how to handle your insurance claim can make the process much smoother. The key is understanding what your policy covers, acting quickly, and communicating effectively with your insurer. With the right tips, you can save time and money while ensuring your vehicle gets back on the road safely.
**Quick answer:** Always review your insurance policy beforehand, document the damage thoroughly, and work with reputable repair shops that handle claims efficiently. Being prepared can turn a stressful situation into a straightforward process.
When a windshield is damaged, it’s easy to feel overwhelmed by the insurance jargon and repair costs. However, with some basic knowledge of how insurance claims work, you can navigate the process confidently. Start by checking your coverage for glass damage, and don’t delay in filing your claim—timeliness can influence your payout. It’s also wise to choose a certified repair shop that works directly with your insurer, streamlining the paperwork and repair process. Understanding your policy limits and deductibles helps set realistic expectations about your out-of-pocket expenses. Armed with these tips, you’ll approach windshield replacement claims with confidence, ensuring a hassle-free experience from start to finish.

Insurance Tips for Windshield Replacement Claims
Understanding Your Insurance Policy
Knowing what your policy covers is the first step toward a smooth windshield replacement process. Many auto insurance policies include comprehensive coverage that pays for glass repairs and replacements. Review your policy carefully to check if windshield repairs are covered without a deductible or if there are specific conditions you need to meet.
It’s essential to understand the terminology used in your policy. Terms like “comprehensive coverage,” “deductible,” and “collision coverage” can impact how much you’ll pay out of pocket. Contact your insurance provider for clarification on any confusing language.
Reporting the Damage Correctly and Promptly
Timely reporting of windshield damage is crucial to prevent worsening of the issue and to ensure your claim is processed efficiently. As soon as you notice a crack or chip, contact your insurance provider to file a claim.
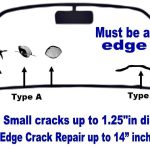
When reporting, provide detailed information about the damage, including the size and location of cracks or chips. Take clear photos of the damage to support your claim and help the adjuster assess the situation accurately.
Choosing the Right Repair Shop
Selecting an authorized or recommended repair shop can influence your insurance claim process. Many insurance companies have trusted providers they prefer to work with, ensuring quality work and proper billing.
Ask your insurance provider if they have a list of approved repair shops. Working with an in-network shop can help you avoid unnecessary out-of-pocket expenses and streamline payment processes.
Another tip is to choose a shop with certified technicians who specialize in windshield replacements. Proper installation is critical for your safety and the longevity of the repair.
Understanding Your Deductibles and Payment Responsibilities
Your deductible amount directly affects how much you pay during a windshield replacement. Some policies feature a zero-deductible coverage for glass repairs, while others may require you to pay a specified amount.
Check your policy documents or speak with your insurer to identify your deductible. If the damage is minor and costs less than your deductible, it might be cheaper to pay out of pocket instead of filing a claim.
Furthermore, clarify whether your insurer covers full replacement costs or only partial expenses, especially if your policy has specific stipulations for glass claims.
Filing Your Claim Correctly
Filing your claim accurately can help speed up the approval process. Provide all required information, including photos, a detailed damage report, and your insurance policy number.
Be honest and thorough in your descriptions to avoid delays or claims denials. Follow the insurer’s specific procedures, whether online, over the phone, or via an app.
Keeping copies of all documents, including receipts and correspondence, can help you track your claim and resolve any issues quickly.

Similar Posts